Navigating mortgage options can be difficult when standard paperwork does not clearly document your earnings. Written Verification of Employment (WVOE) lets a lender obtain employment and income information directly from your employer. Certain mortgage programs use this documentation route for eligible wage earners.
Key Takeaways
- WVOE programs serve eligible wage earners. Self-employed borrowers may need a bank-statement, 1099, or other documentation route.
- Written Verification of Employment documents employment and compensation; approval still depends on the full loan review.
- Verification methods include employer forms, verbal confirmation, paystubs, tax records, third-party services, and program-specific alternatives.
- Non-QM loans offer alternative qualification options. Covered consumer mortgages still require an ability-to-repay review.
This article explains what WVOE means, how lenders verify employment, and what to review before applying. It also distinguishes WVOE from bank-statement and 1099 programs for self-employed borrowers.
So get ready; we’re about to embark on an insightful journey down the less-charted path towards homeownership!
What is Written Verification of Employment (WVOE) and Why is it Important?
Written Verification of Employment (WVOE) is one way to document employment and income for a mortgage. It helps a lender evaluate the income used to qualify you and your ability to repay. It is not the only permitted verification method for every mortgage.
Different types of verification methods exist, ensuring that lenders have accurate information about an applicant's employment status and compensation structure.
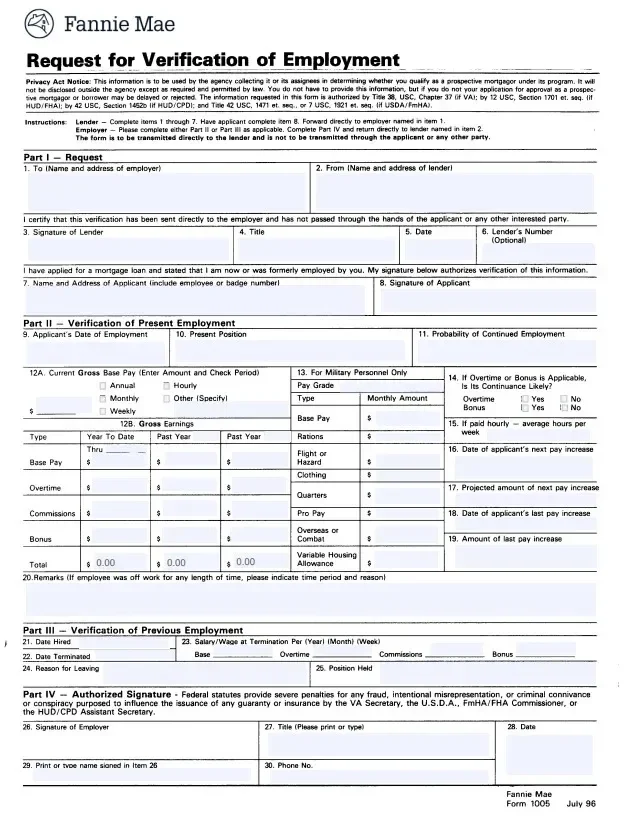
Fannie Mae VOE Form - 1005
WVOE as a requirement for mortgage loans
Mortgage lenders use the Written Verification of Employment (WVOE) to confirm income stability, verifying specific details about an applicant's work history. This process enables lenders to underwrite your financial credentials confidently.
A WVOE mortgage does not have one universal credit-score, loan-to-value, or employment-history requirement. Those limits come from the selected lender program. Fannie Mae Form 1005 records current and previous employment information; the form itself does not require two years with the same employer.
The lender must follow the documentation rules for the selected loan and income type. Fannie Mae permits employer-provided Form 1005 documentation, but that does not mean every loan can omit tax returns, paystubs, or other supporting records.
Verification of income and stability
Lenders often assess your income and stability to determine how capable you are of making timely mortgage payments. Written Verification of Employment, also known as WVOE, plays a crucial role in this process.
It helps us authenticate the borrower's employment status and salary details provided on the loan application.
The WVOE form provides lenders with specific information about an applicant's work history including dates of hire, compensation structure, year-to-date earnings, potential bonus or commission details.
Purchase, refinance, cash-out, and debt-to-income limits depend on the lender and transaction. Confirm the current program matrix before relying on a quoted maximum or assuming cash-out is available.
Self-employed business income requires its own eligible documentation method. An employer verification for wages should not be treated as a substitute for documenting business income.
Different types of verification of employment
Lenders use various methods to verify a borrower's employment and income status. Here are some common types of verification:
- Written Verification of Employment (WVOE): With your authorization, the lender sends the verification request directly to your employer. The employer completes the applicable information and returns it directly to the lender.
- Verbal Verification: The lender directly contacts the HR department or another authorized person in your company to confirm your employment.
- Pay Stub Verification: You provide recent pay stubs as proof of income and ongoing employment.
- Tax Return Verification: Lenders may ask for tax returns or W-2 forms from previous years to confirm consistent income levels.
- 1099 Income Program: Some lenders offer a separate documentation option for eligible independent contractors. Qualifying income is calculated under that program, rather than automatically treating all gross 1099 receipts as wages.
- Bank Statements: A separate bank-statement program may evaluate eligible self-employed income using personal or business deposits and the lender's expense analysis. Deposits are not automatically the same as qualifying income.
Explore WVOE Mortgage Financing
Discuss financing options for your property and financial goals.
- Loan Options
- Estimated Payments
- Property Review


Understanding Non-QM Mortgages
Non-qualified mortgages, or non-QM loans, do not satisfy the applicable Qualified Mortgage criteria. This is a different question from whether Fannie Mae or Freddie Mac will buy the loan. For covered consumer mortgages, lenders still must make a reasonable, good-faith ability-to-repay determination.
With non-QM mortgages, lenders consider other aspects of a borrower's financial profile, such as bank statements and credit history, rather than just relying on standard income verification methods like tax returns or W-2s.
Alternative documentation can help an eligible borrower present income that does not fit a conventional documentation route. Compare the actual interest rate, APR, fees, down payment, and repayment terms; flexibility does not guarantee approval or a lower cost.
It's important to weigh the benefits and considerations before deciding if a non-QM mortgage is the right fit for you.
How to Get Approved for a WVOE Mortgage
Getting approved starts with confirming that your employment, income documentation, credit profile, and property fit the lender's current WVOE program. The steps below explain what the lender reviews.
Don't miss out on this valuable information - read more now!
Who should consider a WVOE mortgage?
A WVOE program may suit a wage earner whose employer can independently verify employment and compensation. For example, Acra Lending describes its WVOE option for wage earners. That does not make it a self-employed or unemployed borrower program.
Depending on the lender, an eligible WVOE route may use employer verification instead of certain standard income documents. Ask for the exact document checklist and disclose any ownership interest in, or family relationship with, your employer.
If you are self-employed, compare bank-statement loans, 1099 mortgage loans, or a conventional loan using the required business-income documentation. Choose the documentation route that matches how you actually earn income.
Steps to getting approved
To get approved for a WVOE mortgage, follow these steps:
- Complete the loan application: Disclose your employment, income, assets, debts, and proposed property accurately. Obtain the lender's program-specific document checklist.
- Authorize employment verification: Give the lender the employer contact information and authorization it needs. The employer should send the completed verification directly to the lender, rather than through you.
- Calculate qualifying income: Work with your lender to calculate your qualifying income based on the information provided in the WVOE form. This may include salary, bonus, commissions, and other sources of income.
- Submit all documentation: Ensure you have submitted all required documentation to your lender, including the completed loan application and supporting financial documents.
- Underwriting process: The lender will review your application and documentation to assess your creditworthiness and ability to repay the loan. They may request additional information or clarification during this process.
- Loan approval: If you meet all the necessary requirements and are deemed eligible for a WVOE mortgage loan, you will receive loan approval from the lender.
What if your employment changes?
If your job ends or changes during the mortgage process, tell your lender promptly. An old employment verification does not establish that discontinued wages remain available to make future mortgage payments.
For a covered mortgage, a lender relying on employment income must consider and verify current employment status under the ability-to-repay rule. Income from another eligible source may support a different qualification route, subject to the lender's requirements.
A 1099 income program is a separate option for eligible independent-contractor income. It is not an unemployment exception to a wage-earner WVOE program, and prior earnings alone do not guarantee approval.
Applying the "Five Cs" for loan approval
The Five Cs provide a useful way to organize the factors a lender reviews: credit history, collateral, capacity to repay, capital reserves, and conditions. Meeting any one factor does not ensure loan approval.
Your credit history plays a major role in determining your eligibility for a mortgage loan. It's essential to maintain a good credit score and have a solid repayment track record. Collateral refers to the value of the property you are purchasing or using as security for your loan.
Lenders will assess this value to determine their risk level. Capacity to repay depends on your income and debt-to-income ratio (DTI). Lenders want assurance that you can comfortably make monthly payments.
Capital reserves show that you have enough funds available for down payment, closing costs, and emergency expenses. Lastly, lenders consider external conditions such as economic factors when evaluating your application.
Exploring Non-Warrantable Condo Mortgages
Non-warrantable condo mortgages may provide financing for a condominium that does not meet an agency program's project requirements. Borrower income eligibility and condo-project eligibility are separate reviews.
A project can be ineligible for reasons such as unresolved significant litigation or property-condition concerns, depending on the applicable guidelines. Do not assume a WVOE income option also accepts non-warrantable condos. Acra's published WVOE program excludes them; another property and documentation combination must be evaluated separately.
Non-warrantable condo mortgages offer an alternative solution for borrowers who want to purchase their dream home in a condominium complex that may not qualify under conventional loan programs.
With flexible lending options and expertise in this area, Bennett Capital Partners Mortgage can provide guidance and support throughout the loan process, ensuring that qualified borrowers can explore all available avenues for homeownership.
Stay Informed with Our FREE Florida Rate Watch Newsletter! If you’re in Florida, don’t miss out on crucial rate updates. Subscribe now and make informed financial decisions.
|
|
Benefits and Considerations of WVOE Mortgage Loans
A WVOE route can reduce certain income-documentation requirements for an eligible wage earner. The benefit depends on the actual program; it does not automatically increase the loan amount or remove the lender's income review.
To learn more about the advantages of WVOE mortgage loans, as well as important factors to consider, continue reading.
When standard income documents may be replaced
Some WVOE programs replace certain paystub, W-2, or tax-return requirements with employer verification. The exact exclusions vary by lender and income type. Request the current written checklist before assuming a document is unnecessary.
Reduced paperwork still requires reliable income information, an eligible property, and satisfactory underwriting. Employer response times and any missing information can affect the process, so a WVOE label does not promise faster approval.
Qualification amounts
Credit-score requirements, maximum loan amounts, LTV or CLTV limits, and DTI limits are lender-specific. A program's advertised maximum is not available to every borrower or transaction.
LTV compares the first mortgage with the property value used for underwriting. CLTV also includes applicable subordinate financing. The permitted ratio may depend on credit, loan purpose, property type, and other restrictions.
For example, Acra's Non-Prime Program Summary dated August 17, 2026 gives WVOE a $150,000 minimum, $1 million maximum, and an 80% CLTV ceiling, with two-year employment and housing histories, primary-residence use, no first-time buyers, and no two-to-four-unit properties. Its credit/transaction matrix and other restrictions can lower the permitted financing. These are one lender's criteria, not universal WVOE limits or a commitment from Bennett Capital Partners.
Eligible properties
The property must meet the selected WVOE program as well as the lender's appraisal and underwriting requirements. Eligible property types may include single-family homes, townhomes, and qualifying condos, with occupancy and project restrictions.
However, there may be certain restrictions or guidelines that lenders have regarding the eligibility criteria. It's important to check with your lender to confirm if the property you have in mind qualifies for a WVOE mortgage.
By doing so, you can ensure that you're focusing your efforts on properties that align with the requirements of this specific loan program.
Specifics of Condo Loans in Florida
For condo loans in Florida, review both the borrower's documentation route and the building's eligibility before choosing a WVOE program.
Ask the lender to confirm the permitted occupancy, condo type, loan amount, credit score, and maximum financing for the specific property. Do not apply a bank-statement program's limits to a WVOE application.
Your employer may be asked to complete Form 1005 or another permitted verification. Employment-history requirements are set by the lender; the form itself does not establish a universal two-year same-employer rule.
If you earn self-employed income or the condo is non-warrantable, a different documentation or property program may be needed. Confirm that the lender accepts both parts of the proposed loan.
Whether you are buying in Miami Beach, Destin, or elsewhere in Florida, have the broker review the proposed property and income documentation together before relying on a financing estimate.
Find the Right Documentation Route
Review your employment, income records, and property with a mortgage broker.
Get a Quote →Conclusion
Understanding WVOE mortgage loans starts with the correct definition: Written Verification of Employment. An eligible wage earner may qualify using employer-verified income under a lender's program, while self-employed borrowers may need a different documentation route.
Compare the required documents, total borrowing costs, property restrictions, and actual qualification limits before applying. Bennett Capital Partners can help review which available financing approach fits your employment and property.
FAQs
What are WVOE loans?
WVOE means Written Verification of Employment. A lender obtains employment and income information directly from an employer. Some mortgage programs use this method for eligible wage earners; it is not a universal no-documentation loan.
How does one start the process for a new home loan using WVOE?
Contact the broker to review your employment, income, credit, down payment, and proposed property. The lender identifies a suitable program and provides its document checklist, including any employer-verification authorization.
Do lenders confer directly with employers during wage verification?
Yes. Employer-provided verification is sent directly between the lender and employer. It can document job dates, pay, and applicable overtime, bonus, or commission earnings. A business profit-and-loss statement is separate from employer wage verification.
Is it possible for everyone to apply for WVOE loans?
No. Eligibility depends on the lender's current program, employment and income, credit, assets, occupancy, and property. Self-employed borrowers may need a bank-statement, 1099, or other eligible documentation route instead.
Does applying for a WVOE loan require any detailed employment records?
The lender needs enough reliable information to document your qualifying employment and income. Some WVOE programs replace certain standard income documents with employer verification, but supporting records may still be required. Ask for the checklist for your exact program.

Sources & Further Reading
- Employment and Income DocumentationFannie Mae | B3-3.2-01, March 4, 2026
- Request for Verification of Employment (Form 1005)Fannie Mae
- WVOE Program OverviewAcra Lending | Wage-earner program example
- Non-Prime Program Summary (PDF)Acra Lending | Version August 17, 2026
- Bank-Statement Program OverviewAcra Lending | Separate self-employed documentation route
- 1099 Program OverviewAcra Lending | Separate independent-contractor documentation route
- What Is a Qualified Mortgage?Consumer Financial Protection Bureau
- Ability-to-Repay RequirementsConsumer Financial Protection Bureau | Regulation Z §1026.43