Bennett Capital Partners Mortgage Brokers helps you compare purchase and refinance options for a Coconut Grove home. Planning an addition or other improvements? Bring the property and the proposed work into the mortgage conversation together.
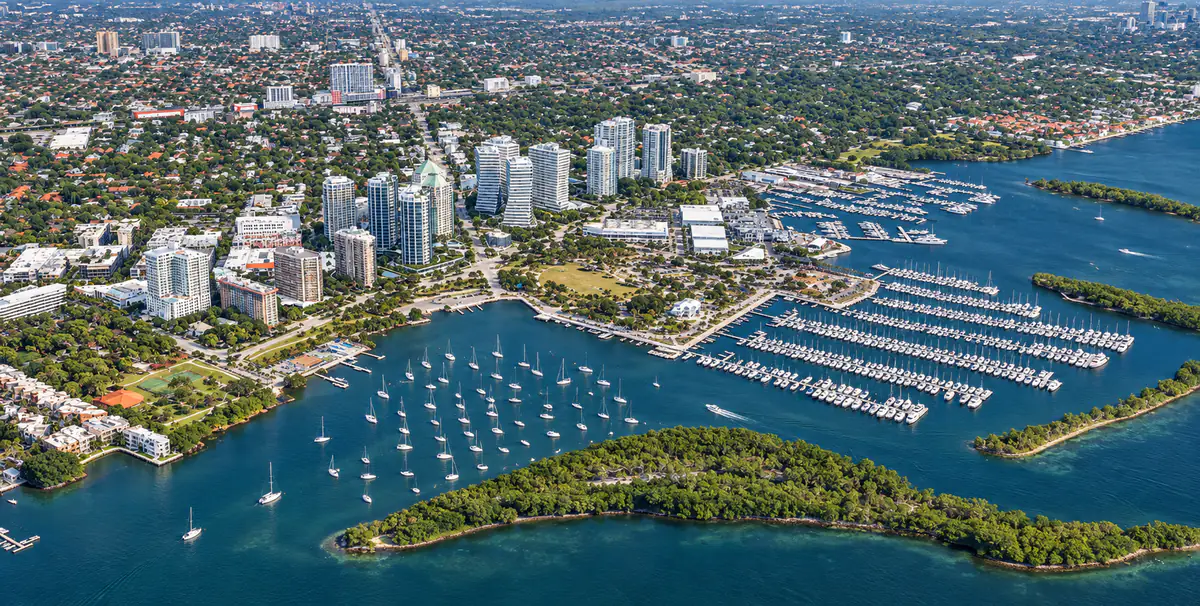
Coconut Grove waterfront and marinas on Biscayne Bay.
Serving Coconut Grove from our Brickell office at 1101 Brickell Avenue, Suite 800, Miami. Company NMLS #2046862.
We are a mortgage broker. Programs and terms depend on borrower, property and lender requirements.
Start with your home purchase or refinance goal.
If no work is planned, compare the purchase or refinance options below using the home's current condition, your income and available funds. If an addition, pool or changed footprint is essential, bring that plan into the same conversation. The parcel checks and worksheet help keep unresolved design and approval questions visible before you commit.
Buying an existing home
Compare conventional mortgages and jumbo loans around your loan amount, income, credit, occupancy and available cash. The home must meet the selected lender's property requirements.
Buying with a defined improvement plan
Renovation financing may combine eligible work with a purchase or refinance. Bring the scope, contractor proposal and known approval questions. A teardown or replacement home calls for a separate construction financing review.
Refinancing a home you own
Review refinance options against your current loan, closing costs and improvement plans. Future financing is subject to qualification and availability; it should not be assumed when deciding what you can afford today.
Buying a condominium? Use our condo financing guide for the separate project review. The property-planning worksheet below focuses on an existing house you intend to change.
Check the Coconut Grove parcel before relying on a renovation concept.
Coconut Grove is a neighborhood within the City of Miami. The City's Neighborhood Conservation District overview identifies NCD-2 and NCD-3 in the Grove. These are zoning overlays. Ask the City which current requirements apply to the exact parcel and proposed work, rather than treating every Grove address alike.
For planned work, ask the City and your design professionals what can proceed, and bring their responses into the lender's property and financing review. Mortgage preapproval does not authorize construction.
Find the address and its zoning.
Start with the City's property zoning lookup instructions. Search the address in the City's GIS tool, review the zoning shown and ask City Zoning about any conservation overlay. If the address or jurisdiction is unclear, confirm it with the City before relying on the result. Give your architect or contractor the exact address and intended changes before relying on a layout or budget.
Check historic designation separately.
Use the City's historic-property lookup as a starting point. If a designation may apply, ask the City's preservation staff what review the proposed alterations need. A neighborhood's age or an older house alone does not establish its designation.
Include trees in the project discussion.
If an addition, driveway or pool concept depends on removing or relocating a tree, identify that dependency before treating the design as settled. The City's tree-permit questionnaire helps identify the relevant process. Ask the City and your qualified project professionals what applies to the specific work.
Request the written information you need.
A City of Miami Zoning Verification Letter can provide requested zoning information, such as the zoning designation, setbacks or nonconformities. Some requests require you to submit supporting documents, such as a survey or plans. It is not a project permit. Confirm its scope and current processing time with the City, then discuss contract timing with your agent or attorney.
The City's NCD overview includes historical proposals. Use it for background, and confirm current parcel requirements with the City. This page does not interpret the zoning code or determine whether a project is permitted.
A worksheet for the property and financing conversation.
For each proposed improvement, record what you know, what remains unconfirmed and who will answer it. Bring the notes to your broker and project professionals. Keep preliminary costs in the plan, clearly labeled as estimates; ask how a changed design or delayed approval would affect the purchase.
Questions to resolve for an existing Coconut Grove house
Write down
Ask the City or project professional
Ask your mortgage broker
Address and proposed work
Which zoning, conservation or historic requirements need review for this parcel and scope?
Which financing paths can be evaluated for the current property and intended work?
A design dependency
Does the addition or pool concept depend on tree work, a changed footprint or another unresolved approval?
What information does the lender need before treating that work as part of the financed project?
Scope and preliminary cost
Which items have written estimates, and which may change after review?
Which costs may be eligible, and which would need separate cash? What contractor documents are required?
Purchase and project dates
What review remains, and how could it change the work schedule?
What conditions affect closing or project funding? What happens if the scope changes?
Cash available after closing
What expenses could arise before work begins or outside the initial estimate?
How much is needed for closing, required reserves and separately funded work without counting the same money twice?
When the addition is still a possibility
Illustrative scenario, not a client transaction: You like a Grove house, but your plans depend on an addition near an existing tree. Keep the addition's cost marked as preliminary while the City and your design professional review the proposal. Ask your broker how the lender would evaluate the purchase and whether a changed scope affects the available financing. Buying the home in its current condition is an option to investigate, subject to property and borrower eligibility.
For detailed program requirements, contractor preparation and funding stages, continue to our Florida renovation loan guide. Fannie Mae's HomeStyle Renovation process illustrates the separate lender review of plans and contractor documentation. Other programs have their own requirements.
Have an address and a few questions about the work?
Our Miami-based team compares financing options around the property, your income documentation, available funds and goals. For renovation plans, we consider the contractor proposal and project alongside the purchase or refinance. We explain the financing requirements and coordinate the submission; the lender makes the underwriting decision.
Describe the purchase or refinance.
Share the address or price range, intended occupancy, down payment and timing. Put any essential changes to the home in the same conversation.
Separate known facts from open questions.
Bring available plans, estimates and City correspondence. Tell us what remains pending so the financing discussion uses the same scope your project professionals are reviewing.
Compare the written costs and conditions.
Consider the payment, cash needed at closing and funds for the work together. Use the CFPB's Loan Estimate comparison guide when comparing lender offers.
Use the previous and next review buttons, swipe, or use the left and right arrow keys to browse reviews. Home goes to the first review; End goes to the last.
“
★★★★★
“He was very responsive and followed the deal all the way through closing.”
Selected excerpts from firmwide Google reviews. These are not presented as Coconut Grove transactions. Read the linked reviews for full context. Individual experiences vary. Testimonials do not guarantee approval, terms, rates or results.
Tell us about your Coconut Grove plans.
Include the property address if you have one, the work you are considering and your expected timing. Tell us which City or project questions are still open.
Please do not send Social Security numbers, account numbers or financial documents through this form. An inquiry is not a loan application or a commitment to lend.
Coconut Grove mortgage questions.
Do you have a Coconut Grove office?
We serve Coconut Grove from our Brickell office at 1101 Brickell Avenue, Suite 800, Miami. Call to discuss your property or view our Brickell office on Google Maps.
Does a conservation overlay mean I cannot renovate?
The overlay alone does not answer what you can do with a particular property. Ask City Zoning about the current requirements for the parcel and proposed work, and have your design professional address them before relying on a final scope.
Does City approval mean the lender will fund the work?
No. Municipal review and mortgage underwriting serve different purposes. The lender separately reviews the borrower, property, program and project requirements, including which costs can be financed.
Can I buy now and finance improvements later?
Possibly, if the home and borrower qualify for the initial loan. Later financing depends on the circumstances and programs available then. Compare that uncertainty with renovation financing, if the property and project qualify, before committing to a purchase that depends on future borrowing.
Is a mortgage broker always less expensive than a bank?
No. Compare written offers for the same scenario, including interest rate, fees, credits, closing costs and conditions. Bennett Capital Partners helps you evaluate available lending options; no single choice fits every borrower.
Financing is subject to lender underwriting, credit approval and property or project eligibility. Program availability and terms can change. Consult the City and qualified professionals about zoning, design, permits and construction. Bennett Capital Partners Mortgage Brokers does not provide legal, tax, architectural or engineering advice. Company NMLS #2046862. Philip Bennett NMLS #1098318. Equal Housing Opportunity.
Explore the best Miami neighborhoods for families, highlighting top schools, safety, parks, lifestyle amenities, and community features that matter most to.
Estimate Florida buyer and seller closing costs with price examples, mortgage and deed taxes, cash-to-close calculations, and ways to reduce upfront costs.
Review conventional loan requirements for credit, DTI, down payment, income, reserves and property eligibility, with current agency rules and lender exceptions.