Bennett Capital Partners Mortgage Brokers helps you compare financing for a Key Biscayne home or condo. Start with the address, how you plan to use the property and the documents available. We can discuss loan options while you confirm insurance, association costs and property records.
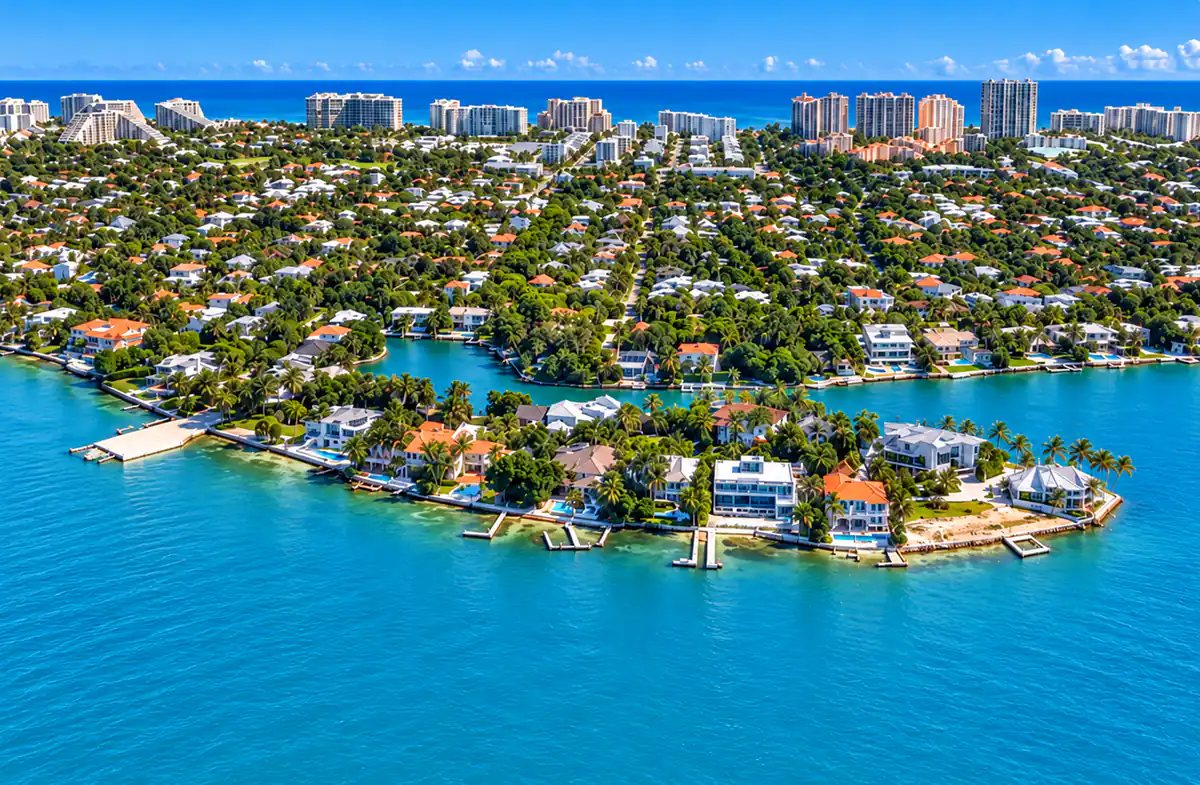
Waterfront homes and coastal condominiums in Key Biscayne, Florida.
Serving Key Biscayne from our Brickell office: 1101 Brickell Avenue, Suite 800, Miami, FL 33131. Company NMLS #2046862.
We are a mortgage broker. The lender determines approval, terms and property eligibility.
Choose financing around the property and its intended use.
Tell us whether this will be your primary residence, a second home or an investment property. The answer affects the mortgage review. A property's location on the island does not establish its loan eligibility.
Home purchase or refinance
Compare conventional financing with jumbo mortgage options when the requested loan amount calls for them. We review the proposed down payment, income documentation and property together. For a refinance, bring your current balance, loan terms and reason for changing the mortgage.
Foreign national programs and bank statement programs address different documentation needs. Discuss your residency, income sources and intended use so we can compare relevant programs. Available terms still depend on the borrower, lender and property.
Build a Key Biscayne property file before finalizing the numbers.
Use the same address and folio number throughout your inquiries. These local checks help your real estate, insurance and financing teams work from the same information. Ask your agent or attorney how to fit them into your contract's review periods.
Request the Village's address-specific flood information.
Find the property's folio through the Miami-Dade Property Appraiser. The Village's flood-information service asks for a street address and folio number. It can provide the mapped Special Flood Hazard Area status, flood zone and base flood elevation or depth shown on its flood map.
Keep the response with the property file. Send it to your insurance agent and ask the lender what coverage it requires. A map description is not a premium quote or a promise that the property will not flood.
Look for the elevation certificate, then confirm any gap.
The Village's elevation-certificate collection organizes available records by year and street address. A certificate missing online may still be in an unscanned file. The page lists this number to confirm whether a certificate not shown online is on file: 305-365-5512.
Ask your insurance professional whether an existing certificate is useful or whether updated information is needed. Before ordering a new survey, ask the seller for any existing certificate and confirm with the Village whether one is on file.
Coordinate the municipal lien search with your closing team.
The Village lien-search service reports open permits, code violations and municipal liens, plus outstanding solid-waste fees for single-family homes and duplexes. Its written request calls for the folio, address and requester's email.
Ask your title professional whether the search has been ordered and who will resolve any findings. Share property-condition or permit questions with the financing team early. This municipal report does not replace title work, inspections or the lender's review.
Confirm rental plans before choosing an occupancy category.
If you may offer the property as a vacation rental, review the Village's short-term rental requirements and the property's association documents. Ask the Village and association to confirm the business tax receipt, lease and rental-period rules for that address.
Then describe the actual plan to the financing team. Permission to rent does not make a property eligible for a particular mortgage. Choose the occupancy category that matches how you will actually use the property.
Missing documents do not have to delay the first conversation.
Start the conversation with the records you have. Mark any missing Village response, insurance quote or association document as outstanding so it remains visible in the financing review.
Compare the full ownership cost, not just principal and interest.
For a condo, separate costs paid through the association from policies you buy yourself. Ask what the dues include so the same expense is not counted twice. Fannie Mae's condo buyer guidance recommends asking about special assessments, association reserves and the scope of the master insurance policy.
Inputs to collect for each Key Biscayne property you are considering
Cost or document
Where to get it
What to record
Mortgage and closing costs
Financing team and lender
Written terms, estimated payment, closing funds and lender-required reserves.
Property taxes
Property Appraiser tax estimator (estimate only)
A purchase-based estimate, not simply the seller's current tax bill.
Association charges
Association or management
Current dues, what they cover, and any approved assessments and payment schedules.
Insurance
Insurance agent, association and lender
Master-policy documents where applicable; unit or home coverage; flood quote, deductibles and effective dates.
Cash remaining
You and your financing team
Funds after closing, known obligations and reserves. Keep a separate allowance for repairs and unexpected expenses.
Illustrative comparison: two properties, different unanswered costs.
You are comparing a condo and a detached home at a similar purchase price. For the condo, management has supplied the dues but the assessment schedule and master-policy details are still outstanding. For the house, you have a homeowners quote but no flood quote. Neither monthly total is complete yet. Mark those items as unknown rather than entering zero, then compare written loan terms once those costs are confirmed. This is a planning example, not a client case or financing offer.
Work with our Miami mortgage broker team on the financing.
Bennett Capital Partners Mortgage Brokers compares available financing using your financial profile and the property file above. Share the Village responses, association information and insurance estimates you already have, and identify missing items. We explain which information needs lender review and help coordinate your mortgage submission; the lender decides eligibility and required coverage. Start with the address or target property type, intended use, expected price or current balance, planned contribution and timing. Keep account statements and other financial documents for the secure application process.
Use the previous and next review buttons, swipe, or use the left and right arrow keys to browse reviews. Home goes to the first review; End goes to the last.
“
★★★★★
“He was very responsive and followed the deal all the way through closing.”
Selected excerpts from firmwide Google reviews. These are not presented as Key Biscayne transactions. Read the linked reviews for full context. Individual experiences vary. Testimonials do not guarantee approval, terms, rates or results.
Key Biscayne mortgage questions.
Does the association's insurance cover everything inside my condo?
Do not assume it does. Request the master-policy documents and ask your insurance agent which parts of the unit, belongings and risks need separate coverage. Have the lender confirm its requirements for the transaction.
Does an island address determine my flood premium?
No single Key Biscayne premium applies to every property. Obtain an address-specific quote and ask the insurer which property details affect it. The Village's flood information can support that discussion, but it is not an insurance quote.
Should I increase the down payment if I have cash available?
Compare the written loan terms and the funds left after closing. A larger down payment reduces the amount borrowed, but leaves less money for other costs. Do not count the same funds as both required reserves and money you plan to spend on an assessment or repairs.
Is your office in Key Biscayne?
Our office is at 1101 Brickell Avenue, Suite 800, Miami, FL 33131. We serve Key Biscayne from that office and through remote communication. Contact us to arrange a conversation.
Tell us about your Key Biscayne property.
Include the address and folio if known, your purchase or refinance goal, intended use and timing. Mention any insurance or association information you are waiting for.
Please do not send Social Security numbers, account numbers or financial documents through this form. An inquiry is not a loan application or a commitment to lend.
Financing is subject to lender underwriting, credit approval and property or project eligibility. Programs and terms can change. Bennett Capital Partners Mortgage Brokers does not provide legal, tax or insurance advice. Company NMLS #2046862. Philip Bennett NMLS #1098318. Equal Housing Opportunity.
Master condo financing problems with our guide. Uncover common issues and solutions. Explore mortgage options with Bennett Capital Partners Mortgage today.